pics five / Shutterstock.com
Dusan Petkovic / Shutterstock.com
Czajnikolandia / Shutterstock.com
brizmaker / Shutterstock.com
Faizal Ramli / Shutterstock.com
Quality Stock Arts/Shutterstock.com
Marina Demidiuk / Shutterstock.com
PeopleImages / Shutterstock.com
Standret / Shutterstock.com
Tom Korcak / Shutterstock.com
PeopleImages / Shutterstock.com
Blue Planet Studio/Shutterstock.com
CarbonNYC [in SF!] / BY 2.0
Grandpa's $19K Gifts Could Jeopardize His Nursing Home Coverage
Giving $19,000 to a child or grandchild can look completely harmless from a tax standpoint. In 2026, that amount falls within the IRS annual gift-tax exclusion. But there is another set of rules older Americans need to know about, especially if long-term care could eventually enter the picture.
Medicaid does not use the IRS gift-tax rules to decide whether a transfer is acceptable. A gift that creates no federal gift-tax filing requirement can still come back into the conversation years later when someone applies for Medicaid coverage for nursing-home or other long-term care services. Here is where the two systems collide, and why a seemingly routine family gift can become surprisingly expensive.
A $19,000 Gift Can Look Completely Safe
Imagine a widower in his late seventies who wants to help his grandchildren while he is still around to enjoy it with them. In 2026, he writes each one a $19,000 check. From a federal gift-tax standpoint, that number makes perfect sense. The IRS annual exclusion is $19,000 per recipient in 2026.
For a qualifying present-interest gift, a donor can generally give up to that amount to each recipient without dipping into the donor's $15 million 2026 lifetime basic exclusion and without filing Form 709, assuming no other reporting rule applies.
Then life throws everyone a curveball. A stroke leads to long-term nursing care, Medicaid becomes part of the conversation, and those perfectly ordinary checks suddenly matter for an entirely different reason.
The IRS and Medicaid Play by Different Rules
This is where families can get tripped up. The IRS annual exclusion is a gift-tax rule. Medicaid's transfer rules help determine eligibility for a needs-based health program. Passing one test does not mean you automatically pass the other.
A $19,000 gift may create no federal gift-tax filing requirement at all, yet Medicaid can still treat it as a transfer for less than fair market value when someone later applies for long-term care coverage. Federal Medicaid law does not create an exemption simply because a gift fell within the IRS annual exclusion.
So when someone says a gift is "tax-free," that may be true. It just does not answer the Medicaid question.
Medicaid Can Look Back Five Years
For most states, federal Medicaid law generally requires a 60-month lookback when someone seeks Medicaid coverage for certain long-term care services. Transfers for less than fair market value made during that window can lead to a period when Medicaid will not pay for the affected long-term care.
The details are not identical everywhere. States have different resource limits, penalty divisors, procedures and exemptions, and California has its own shorter framework. That is why blanket statements about a universal "$2,000 Medicaid asset limit" can be seriously misleading.
The larger point is simple: money given away years before anyone expected a nursing-home stay can still show up in the financial history Medicaid reviews.
A Gift Inside the Lookback Is Not an Automatic Penalty
There is an important bit of breathing room here. Federal law provides an exception when an applicant can satisfactorily show that assets were transferred exclusively for a purpose other than qualifying for Medicaid.
That could matter for our grandfather. If he was healthy, routinely gave money to his grandchildren and had no reason to anticipate needing Medicaid long-term care, those facts and records may help show that qualifying for Medicaid was never the point of the gifts.
That does not guarantee the state will accept the argument. The facts, documentation and state procedures matter. The accurate takeaway is that gifts within the lookback can trigger scrutiny and potentially a penalty, but a penalty is not automatic simply because a gift occurred.
The Penalty Can Start at the Worst Possible Time
This is one of the nastier parts of the rule. For transfers made on or after Feb. 8, 2006, the penalty generally does not simply burn itself off while someone is still healthy and living at home. Under federal law, it can begin when the applicant is otherwise eligible for Medicaid and would be receiving institutional-level care if the transfer penalty did not exist.
In plain English, the problem can finally become real at exactly the moment the nursing-home bills start arriving.
The penalty also does not necessarily wipe out every form of Medicaid coverage. It targets the affected long-term care services, while other Medicaid services may remain available depending on the person's eligibility and state rules.
Three $19,000 Gifts Can Add Up Fast
The penalty calculation generally starts with the total uncompensated value of the assets transferred and divides it by the state's applicable average private-pay nursing-facility cost.
If the grandfather gives three grandchildren $19,000 each, that is $57,000 in transfers. Using a purely illustrative state divisor of $12,000 per month, the calculation would produce a 4.75-month penalty period. Four $19,000 gifts would total $76,000 and work out to about 6.33 months under the same example.
Those figures are illustrations, not a national penalty schedule. States use their own applicable divisor, and federal law prohibits states from simply rounding away the fractional portion of a penalty period.
Medicare Usually Won't Save the Day
It is easy to assume Medicare will simply step in if Medicaid does not pay. For long-term custodial nursing-home care, that usually is not how it works. Medicare Part A can cover qualifying short-term skilled nursing-facility care for up to 100 days in a benefit period when its requirements are met, but it does not cover long-term custodial care when that is the only care someone needs.
That is one reason Medicaid plays such a large role in long-term care. KFF's 2025 data shows Medicaid as the primary payer for about 63% of residents in certified U.S. nursing facilities.
If a Medicaid transfer penalty kicks in, there is not necessarily another federal program waiting in the wings to pick up months of private-pay nursing-home bills.
A Few Months of Private-Pay Care Can Hurt
Nursing-home care is expensive enough that even a relatively short penalty can do real damage to a family's finances. CareScout's 2025 Cost of Care Survey puts the national median at $10,798 per month for a private nursing-home room and $9,581 for a semi-private room. The corresponding annual medians are $129,575 and $114,975.
Location can make the bill considerably worse. CareScout puts the 2025 median annual cost of a private room at $221,372 in Oregon and $191,625 in Washington.
At national rates, several months without Medicaid long-term care payment can easily mean tens of thousands of dollars out of pocket. In especially expensive states, a longer penalty can push the total into six figures.
California Plays by a Different Rulebook
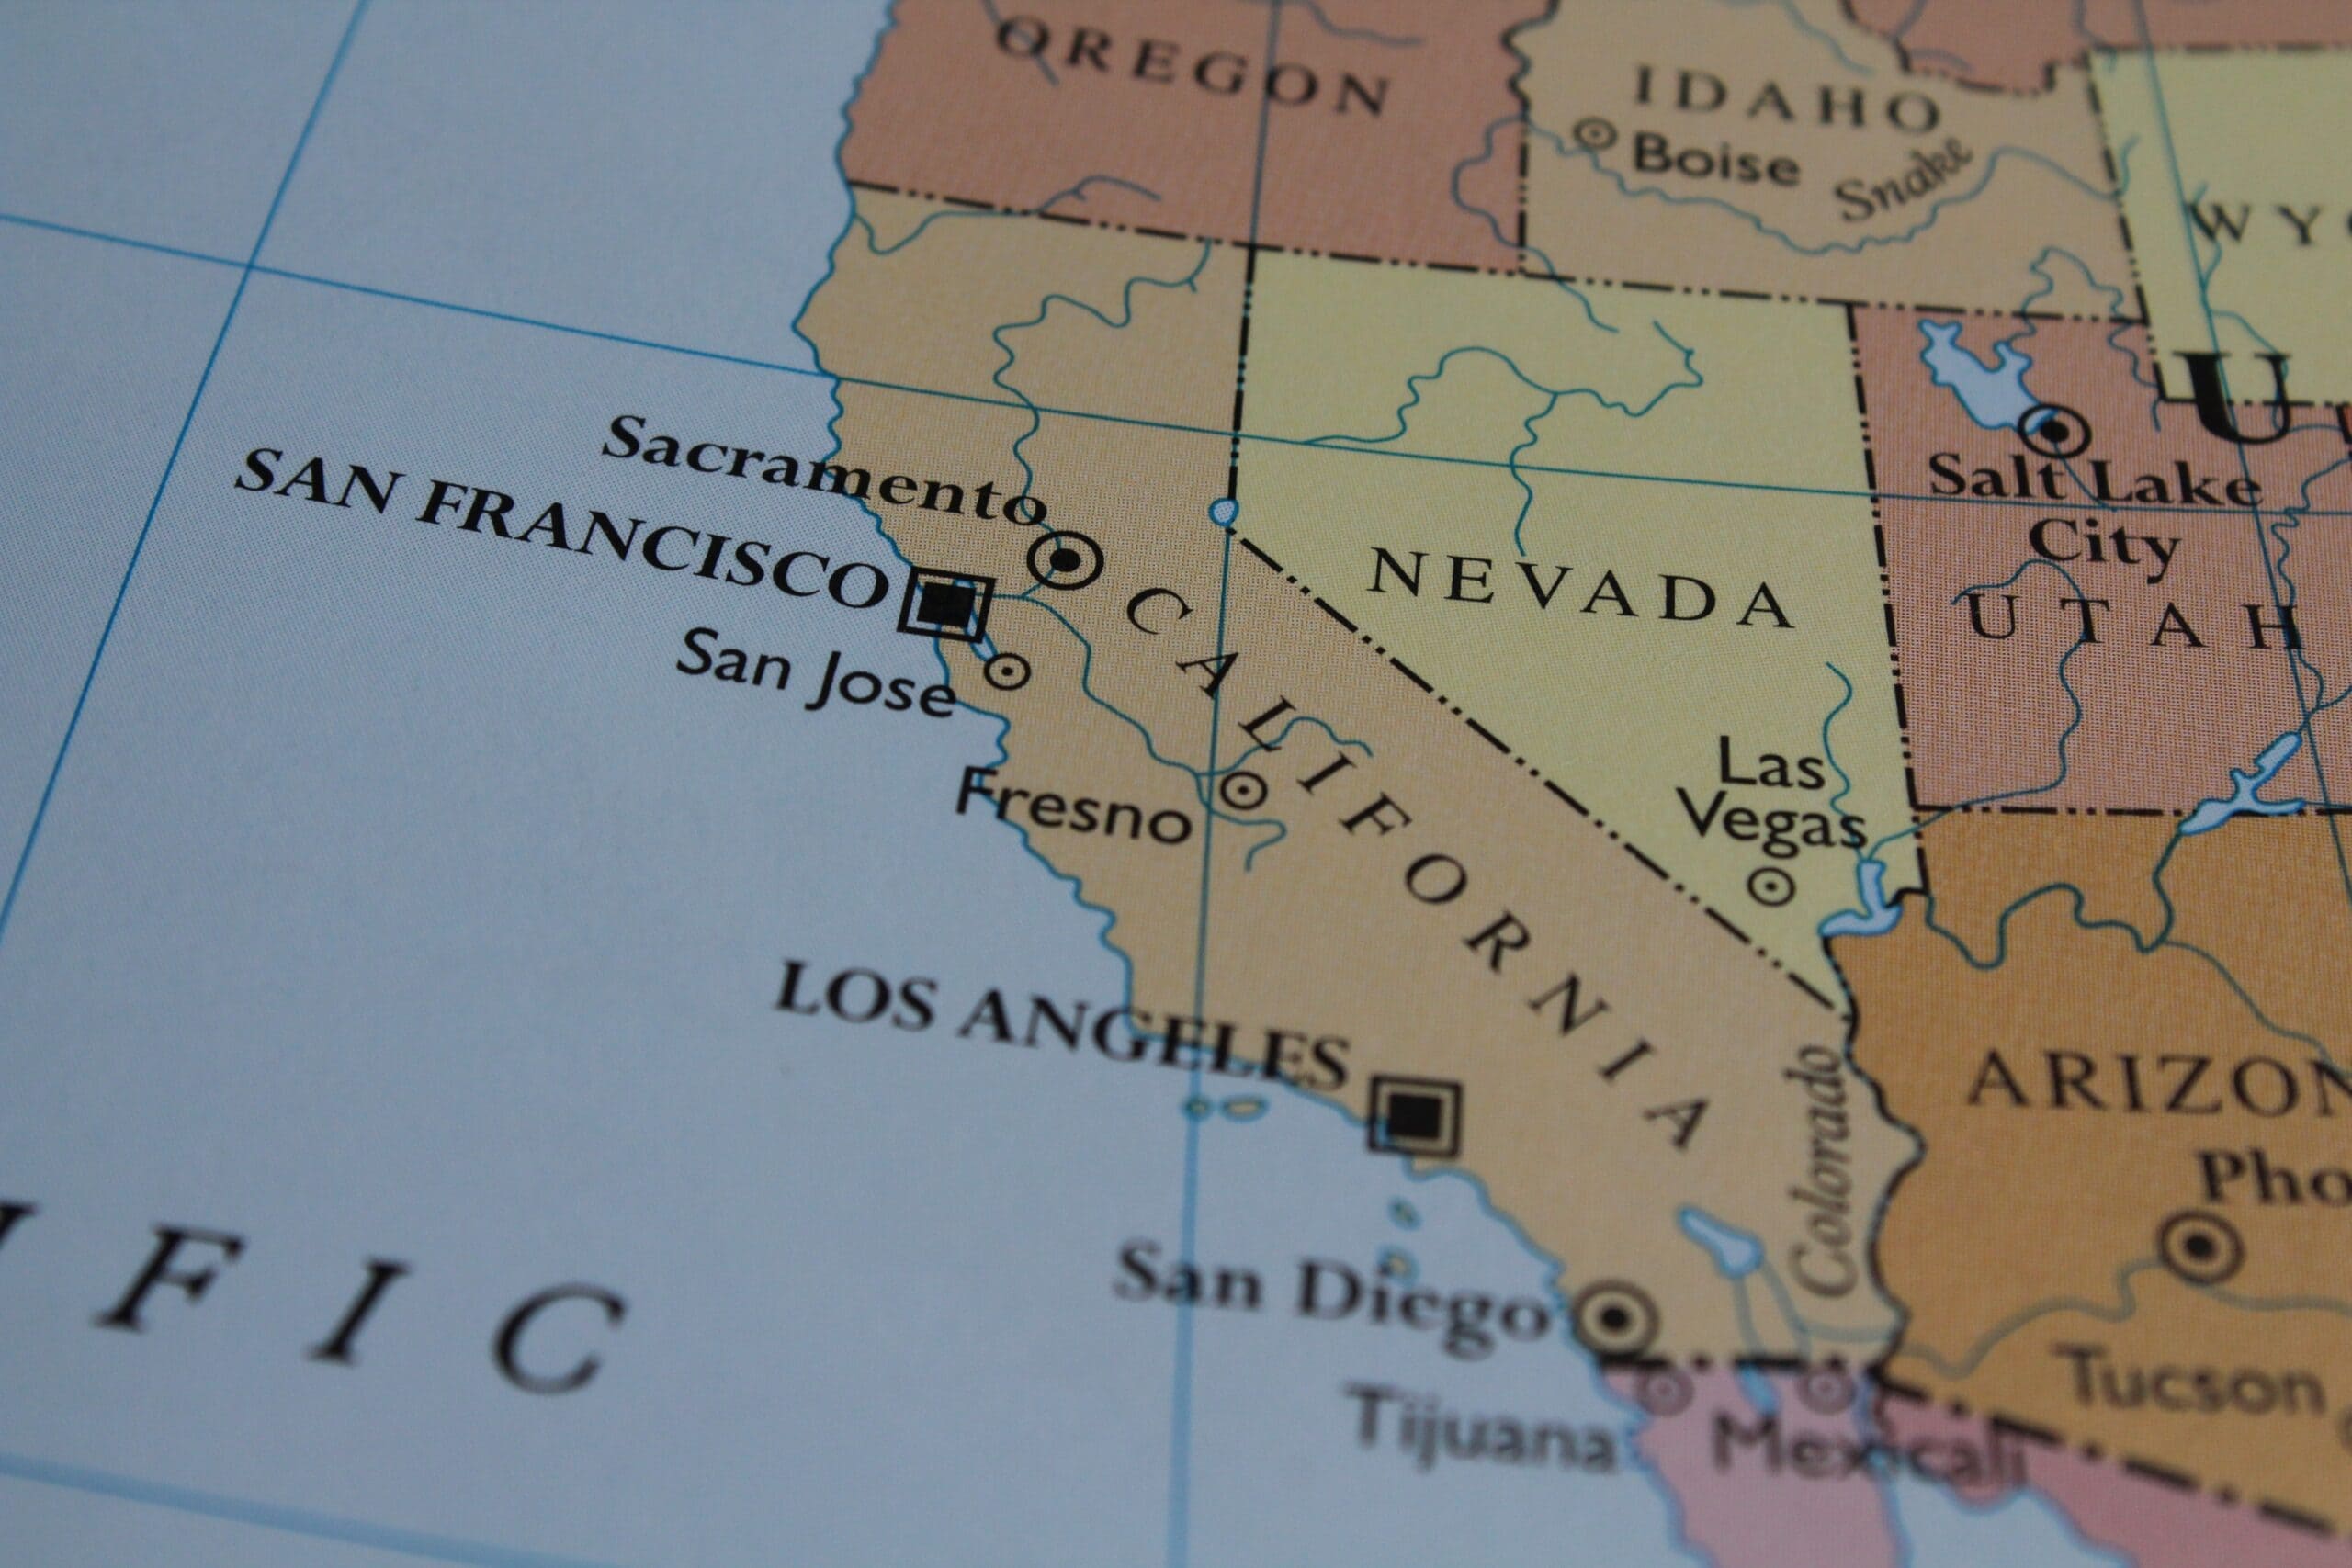
California is a major exception to the usual five-year framework. Medi-Cal uses a maximum 30-month transfer lookback for long-term care, and the state is currently phasing that review period back in after eliminating its asset test during 2024 and 2025.
Transfers made from Jan. 1, 2024 through Dec. 31, 2025 are not included in the review. Transfers made on or after Jan. 1, 2026 can count, and beginning in July 2026 the number of post-2025 months reviewed increases month by month. The full 30-month review is scheduled to apply to long-term care applications and entries beginning July 1, 2028.
California also reinstated an asset test in 2026, with a $130,000 limit for one person through June 30, 2027. It is a good example of why Medicaid planning needs to be based on current state rules, not a national rule of thumb someone remembers from five years ago.
Family Members Are Not Automatically on the Hook
A Medicaid penalty can leave a serious payment gap, but that does not mean the nursing home can simply hand the bill to the resident's children or grandchildren. Relatives do not automatically become personally liable just because they are family.
Federal nursing-home rules prohibit a certified facility from requiring a third party to personally guarantee payment as a condition of admission, expedited admission or continued stay. Someone who legally controls the resident's money can be required to use the resident's available funds to pay the facility, but that is very different from promising to pay the bill out of the representative's own pocket.
The resident's own available resources can still be pursued, and unpaid bills can create transfer or discharge issues subject to federal and state protections. Families may decide to help voluntarily, but the Medicaid penalty itself does not turn the grandchildren into guarantors.
Some Transfers Are Protected, and Some Can Be Fixed
Not every transfer creates a Medicaid penalty. Federal law protects several categories, including transfers to a spouse, certain transfers involving a blind or disabled child, and qualifying transfers of a home to particular family members when the legal requirements are met.
There is also a potential way to undo a bad transfer. Federal law provides that the penalty does not apply when all assets transferred for less than fair market value have been returned to the applicant. How partial returns are handled and exactly how a transfer is cured can depend on state rules.
States must also provide an undue-hardship process when applying the penalty would endanger a person's health or deprive the person of necessities such as food, clothing or shelter. It is a narrow protection, but it means a transfer penalty determination is not necessarily the end of the road.
Before Writing the Check, Run Both Sets of Rules
The takeaway is not that grandparents should stop helping their kids or grandchildren. It is that "$19,000 is allowed" answers a federal gift-tax question, not a long-term care planning question.
Before an older person makes a significant gift, it is worth understanding the state's Medicaid lookback period, resource limits, current penalty divisor and how much money would remain available if long-term care eventually had to be paid privately. Good records showing when and why gifts were made can also become valuable years later.
For anyone facing a significant transfer or a realistic possibility of needing long-term care, an elder-law attorney familiar with the donor's state rules can evaluate the Medicaid side while a tax professional handles the tax consequences. There are two rulebooks here. Problems tend to start when a family checks only one.